Investment loans

Structured by someone who has done the deals herself

Lisa Shen has spent 20+ years acquiring sites, running feasibilities and financing developments. That's the experience behind every investment loan we structure — from a first rental to a growing portfolio.

The difference experience makes

Most brokers read about property. Lisa has built it.

Feasibility, holding costs, construction drawdowns, the sprint to refinance before an interest-only cliff — Lisa has managed all of it with her own projects on the line.

  • Loan structures that anticipate the next purchase, not just this one
  • Lender selection sequenced to protect portfolio borrowing power
  • Construction and development finance handled in-house
  • Fluent in the numbers investors actually care about: yield, LVR, serviceability
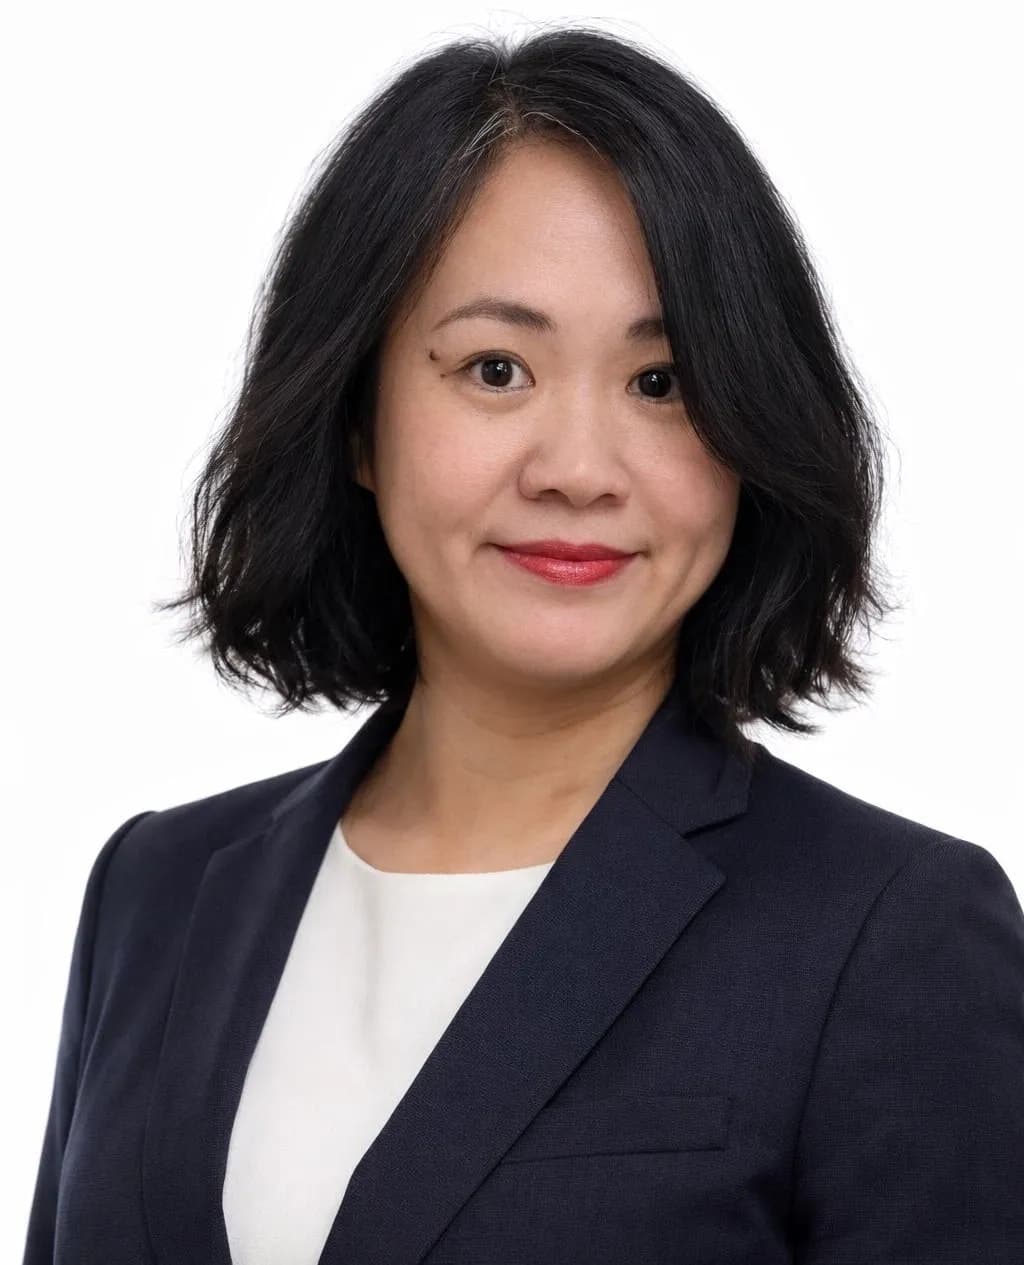
Lisa Shen, who brings 20 years of property development experience to investment lending

The structural choice

Interest-only vs principal & interest

The most consequential decision on an investment loan isn't the rate — it's the repayment structure. Here's the honest trade-off.

Cash flow & deductibility

Interest-only

  • Lower repayments while the IO period runs — typically up to 5 years
  • Keeps investment debt (generally deductible) high while you attack non-deductible home debt
  • Standard practice during construction, renovation or lease-up phases
  • Costs more over the life of the loan, and repayments step up when the IO period ends

Equity & price

Principal & interest

  • Consistently cheaper rates than interest-only lending
  • Every repayment builds equity you can recycle into the next purchase
  • Easier serviceability treatment with many lenders across a portfolio
  • Higher repayments from day one — less spare cash flow while you hold

Which one suits you depends on tax position, cash flow and what the property needs to do in your plan. Read Lisa’s full explainer or ask us to model both.

Using what you've built

Turning equity into your next deposit

Most investors don't save their second deposit — they release it. Done in the right order, it protects both your tax position and your future borrowing power.

  1. 01

    Establish usable equity

    Most lenders will lend against 80% of your property's value (sometimes more with LMI). Usable equity is that figure minus your current loan balance.

  2. 02

    Release it the right way

    A separate split or line of credit keeps investment borrowing cleanly separated from personal debt — which your accountant will thank you for at tax time.

  3. 03

    Deploy as your deposit

    The released equity becomes the deposit and costs on the investment purchase, often letting you buy without touching cash savings.

  4. 04

    Structure for the next one

    Avoiding cross-collateralisation and choosing lenders in the right order preserves borrowing power for purchase two, three and beyond.

Good to know

Investment lending, answered

Straight answers on deposits, structures and the mechanics of building a portfolio.

Usually 10–20% of the purchase price plus costs, though many investors use equity in an existing property instead of cash. With 20% down you avoid Lenders Mortgage Insurance; some lenders accept less for strong applicants.

Take the first step

Planning your next purchase?

Bring your numbers — or just your idea. A free assessment maps your equity, capacity and structure options across 50+ lenders.

FBAA accredited member50+ lenders on panelCredit Rep 524535

Book free assessmentCall